Playtech, 888/Evoke, Playtika, Moon Active, Plarium, SBTech inside DraftKings, Optimove, NeoGames, SciPlay — and the Cyprus-Malta-Gibraltar offshore corridor. The most successful Israeli export category nobody talks about. The complete map.
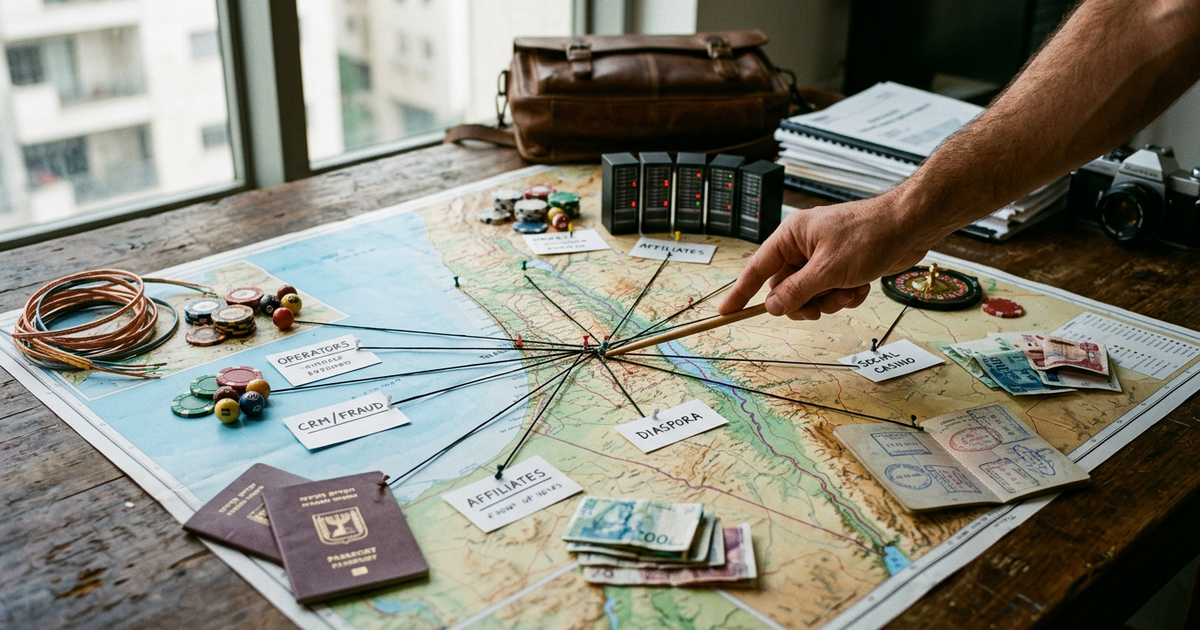
Forty-plus Israeli-founded or Israeli-engineered companies built and still operate most of the modern online gambling industry — operators, B2B platforms, social-casino studios, affiliates, fraud and CRM infrastructure, and the offshore diaspora that runs it today. Israel banned most of it at home while exporting the entire back-end. The complete map.
The Israeli iGaming complex is the most successful export category almost nobody talks about. It runs from the Tel Aviv engineering culture of the late 1990s and early 2000s, through the offshore licensing corridor in Cyprus, Malta, and Gibraltar, into the operating companies and B2B platforms that power the world's largest sportsbooks, casinos, and social-casino apps. And it does so while the domestic gambling market is a state monopoly that would look small next to Playtika alone. Cumulative Israeli-founded iGaming enterprise value across the past three decades runs comfortably into the tens of billions of dollars, and the category remains one of the highest-margin operating industries the Israeli technology economy has produced.
How Tel Aviv built the modern online gambling category, 1997–2010
How Tel Aviv Built Online Gambling. Between 1997 and 2010, a small cluster of Tel Aviv engineering teams built the back-end of the global online gambling industry. The founding conditions were three-part: a domestic engineering pipeline coming out of Israeli military technical training, an offshore licensing corridor (Cyprus, Malta, Gibraltar) that provided regulatory jurisdiction for products the domestic Israeli market did not permit, and a global consumer market that was digitizing gambling faster than any incumbent European or US operator was prepared to serve. The Tel Aviv engineering cluster hit that window with founder cohorts that stayed operationally involved for decades.
Playtech: Teddy Sagi's B2B platform empire
Playtech: Teddy Sagi's B2B Empire. Founded 1999 with engineering rooted in Israel from the start. Listed on the London Stock Exchange (LSE: PTEC). The back-end behind William Hill, bet365 partners, and dozens more. Sagi's bet was that operators would change but the platform would compound. Two decades later it has.
The Playtech commercial architecture — global B2B software licensing to regulated operators across dozens of jurisdictions, with Cyprus-domiciled holding structure and Tel Aviv engineering base — became the reference template for the entire Israeli iGaming category. In 2021, Aristocrat Leisure bid £2.1 billion to acquire Playtech — the offer ultimately lapsed after shareholders rejected it in February 2022, but the attempt valued the platform at a premium that confirmed the category's institutional credibility. Playtech sold its Snaitech retail unit to Flutter Entertainment in 2025 to refocus as a pure-play B2B supplier.
Sagi's post-Playtech portfolio (Camden Market, Kape Technologies, and dozens of adjacent positions) is the operative case study in how iGaming founding capital compounds outside the category.
888 Holdings / Evoke: the Shaked and Ben-Yitzhak operator franchise
888 Holdings / Evoke plc (LSE: EVOK). Founded May 1997 by Israeli brothers Avi and Aaron Shaked and Shay and Ron Ben-Yitzhak as Virtual Holdings Ltd. Launched Casino-on-Net in 1997, listed in London in 2005, acquired William Hill's international business in June 2022 for £1.95 billion, rebranded to Evoke.
The William Hill acquisition proved transformative — and punishing. Evoke carried approximately £1.8 billion in debt at year-end 2025. Evoke launched a strategic review in December 2025 in response, and on June 5, 2026, agreed to be acquired by Greek gaming group Bally's Intralot for approximately £243.1 million; Evoke shareholders approved the deal in August 2026, with completion expected in Q4 2026 or Q1 2027.
888/Evoke is the reference case for the operator side of the Israeli iGaming category — and for operator leverage risk. The trajectory across three decades is the category's canonical demonstration that Israeli founders can build and operate at global scale in the operator layer. It is also a demonstration that operator economics — higher variable marketing spend, more direct regulatory exposure, closer proximity to the consumer relationship — carry structural fragility that B2B platform economics do not.
Playtika: the social-casino category on Nasdaq
Playtika: The Israeli Social-Casino Franchise That Threaded Three Ownership Regimes to Reach Nasdaq. Founded 2010 in Herzliya by Robert Antokol and Uri Shahak. Sold to Caesars in 2011, then to a Chinese consortium led by Yuzhu Shi (Giant Network) in 2016 for $4.4 billion, then Nasdaq IPO in January 2021 at roughly $11.1 billion.
Playtika sits inside the iGaming complex as its largest publicly listed expression, with the Slotomania/Caesars Slots/House of Fun/Bingo Blitz/WSOP franchise portfolio and hundreds of millions of dollars in annual free cash flow as of 2026. See the founder profile at Robert Antokol: The Man Behind Playtika.
In 2022, Joffre Capital agreed to acquire the controlling stake held by the Chinese consortium at an $8.5 billion valuation — a premium to the trading price at the time, though below the IPO valuation. Playtika remains listed on Nasdaq (PLTK).
The social-casino category — free-to-play, in-game virtual currency, outside real-money gambling licensing regimes — is structurally distinct from the operator and B2B layers of the iGaming complex but shares the same Tel Aviv engineering base and the same founder-cohort continuity.
Moon Active: the privately held social-casino giant
Moon Active and Coin Master: The Social-Casino Blur. Founded 2011 in Tel Aviv by Samuel Albin. Coin Master — slot-mechanic casual game, no real-money cash-out — crossed $6 billion in lifetime revenue by 2024 on just $10 million in primary capital raised. Valued above $5 billion in the November 2021 secondary round led by Insight Partners with Andalusian Private Capital participating. Cut 110 employees (5% of workforce) in January 2026 as part of operational restructuring. Remains private — the largest Israeli gambling-adjacent company never to list publicly. See the founder-level profile at Moon Active: The Israeli Company Behind Coin Master.
Plarium: from Herzliya to Aristocrat to MTG
Founded 2008 in Israel by brothers Avi and Gabi Shalel and Haim and Ilya Turpiashvili. Built Raid: Shadow Legends and a portfolio of strategy-RPG titles with casino-mechanic engagement loops underneath. Acquired by Aristocrat in 2017 for approximately $500 million. In November 2024, sold to Sweden's Modern Times Group (MTG) for up to $820 million — $620 million fixed plus $200 million in performance-based payments through 2028. Management remains predominantly based in Israel. Plarium demonstrates the Israeli iGaming pattern extended into strategy gaming: the engagement mechanics are casino-derived, the engineering base is Tel Aviv, the holding structure is offshore, and the exits are international.
SBTech inside DraftKings: the US sports-betting engine
Shalom Meckenzie: The SBTech Founder Behind DraftKings. The Diamond Eagle SPAC merger, the PASPA opportunity, and the Tel Aviv code inside America's second-largest sportsbook. SBTech's integration into DraftKings (NASDAQ: DKNG) via the 2020 SPAC transaction, valuing the combined company at roughly $3.3 billion, is the most operationally consequential Israeli iGaming transaction of the past decade — it placed Israeli sports-betting engineering at the operational core of the US sports-betting category at the moment PASPA opened the market to state-by-state legalization.
NeoGames, SciPlay, and the second-tier operator layer
Below the anchor names, the Israeli iGaming complex includes a broader second-tier layer. NeoGames — iLottery and iGaming platforms founded by Barak Matalon — is now integrated into Australian-headquartered Aristocrat as Aristocrat Interactive. See NeoGames: Barak Matalon's Israeli iLottery Company and Aspire Global: Barak Matalon's Other iGaming Company. SciPlay — social casino — is inside the Light & Wonder architecture with a substantial Israeli engineering base.
The infrastructure layer: CRM, fraud, and adtech
The Israeli iGaming complex extends well beyond operators and studios into the infrastructure that powers them.
Optimove — founded in Tel Aviv — built the dominant CRM platform for iGaming operators. In April 2026, Optimove acquired Smartico, the gamification and CRM engagement platform, consolidating Israeli-rooted infrastructure across the iGaming CRM stack. Optimove's client base spans major sportsbooks, online casinos, and lottery operators globally.
The affiliate, fraud-detection, payment-processing, and user-acquisition layers include dozens of additional Israeli-founded or Israeli-engineered companies operating across the category. A Remagine Ventures mapping identified 143 active Israeli gaming companies — 63 studios, 20 adtech/user-acquisition startups, and 55 active investors — with $3.65 billion in disclosed exits. The gambling-adjacent subset of that ecosystem is the infrastructure layer of the iGaming complex.
The cumulative footprint places Israeli engineering at roughly every layer of the modern iGaming stack, from B2B platforms through operator brands through consumer applications through the CRM and engagement infrastructure that ties them together.
The Cyprus–Malta–Gibraltar offshore licensing corridor
Playtech, 888/Evoke, NeoGames, SciPlay, Aristocrat's Israeli backbone, and the Cyprus–Malta–Gibraltar corridor host the licensed industry. The offshore-licensing corridor is one of the operative structural features of the Israeli iGaming category that no other national iGaming ecosystem replicates at the same intensity. Cyprus provides the primary holding-company jurisdiction for much of the category. Malta and Gibraltar provide operating licenses for consumer-facing gambling products. The corridor emerged in the late 1990s and early 2000s in response to the domestic Israeli regulatory frame that prohibits most forms of online gambling inside Israel, and it has remained the operative jurisdictional layer of the category throughout its four-decade build. See also How The Operators Rebuilt In Regulated Markets.
The domestic irony: Mifal HaPais, Toto, and the Israeli state-monopoly frame
Mifal HaPais & Toto: Israel's Gambling Irony. Israel built the modern online gambling industry while banning most of it at home. The state monopolies — Mifal HaPais (national lottery) and Toto (sports betting) — contain the domestic Israeli gambling market inside a highly regulated frame, while the Israeli-founded companies exporting into the licensed international market operate outside that frame through offshore-domiciled subsidiaries. The Knesset debate over expanding the domestic gambling market recurs periodically and has not, to date, materially reshaped the category. The domestic constraint is one of the operative structural reasons the Israeli iGaming category built as an export industry from the founding, rather than as a domestic-market industry that later internationalized.
How the layers compare
| Company | Category | Position | Enterprise Value / Exit |
|---|---|---|---|
| Playtech (LSE: PTEC) | B2B platform | Dominant global gambling software | £2.1B Aristocrat bid (lapsed 2022) |
| 888 / Evoke (LSE: EVOK) | Operator | Founded 1997; acquired William Hill international £1.95B | £243.1M Bally's Intralot acquisition, shareholder-approved Aug 2026, closing expected Q4 2026/Q1 2027 |
| Playtika (NASDAQ: PLTK) | Mobile / social casino | $4.4B exit → ~$11.1B Nasdaq IPO 2021 | $8.5B Joffre controlling-stake valuation (2022) |
| Moon Active | Mobile / social casino | Coin Master; $6B+ lifetime revenue | $5B+ valuation (2021 secondary) |
| Plarium | Strategy / social casino | Raid: Shadow Legends; Israeli-managed | $500M (Aristocrat 2017) → $820M (MTG 2024) |
| SBTech | Sports betting engine | Inside DraftKings (NASDAQ: DKNG) via SPAC | ~$3.3B combined DraftKings valuation at merger |
| NeoGames | iLottery and iGaming | Part of Aristocrat Interactive | $1.2B Aristocrat acquisition (2023-2024) |
| SciPlay | Social casino | Inside Light & Wonder with Israeli engineering | Public (NASDAQ: SCPL) |
| Optimove | CRM / infrastructure | Dominant iGaming CRM; acquired Smartico (2026) | Private |
| Mifal HaPais / Toto | Domestic | State monopoly; contains the domestic market | State-owned |
The complete iGaming series
- How Tel Aviv Built Online Gambling
- How The Operators Rebuilt In Regulated Markets
- Playtech: Teddy Sagi's B2B Empire
- The Playtech Founder Who Owns Camden
- 888 Holdings / Evoke plc
- Playtika: Three Ownership Regimes to Nasdaq
- Robert Antokol: The Man Behind Playtika
- Shalom Meckenzie: SBTech and DraftKings
- Mifal HaPais & Toto: The Domestic Irony
- Moon Active and Coin Master: The Social-Casino Blur
- NeoGames: Barak Matalon's Israeli iLottery Company
- Aspire Global: Barak Matalon's Other iGaming Company
How we report: Olam stories draw on public filings, company disclosures and named sources, checked by our editors. Read our methodology · Corrections