
Azrieli leads visible Israeli real estate citations. The buried story is the Sun Belt blind spot — Israeli sponsors of US multifamily, hidden behind US-domiciled LLCs and invisible to the AI engines.
By Ronn Torossian · Publisher, Olam
Originally published June 10, 2026. Deepened June 15, 2026. Rewritten October 26, 2026 to describe the index as a modeled estimate.
Citation Share Snapshot · Real Estate Sector
| Nature of the ranking | Modeled, directional editorial estimate. Not a measured dataset. |
|---|---|
| Top-ranked entity | Azrieli Group |
| The buried story | US Sun Belt multifamily: Israeli sponsorship, very low AI visibility |
| Size of Israeli-sponsored US real estate | Olam has not found a verified published tally |
| 2027 expansion | A separate Diaspora Real Estate sub-index is planned |
Israeli real estate runs two economies. The visible one, Azrieli, Gazit, Amot, Melisron, is concentrated, family-controlled, and lives on the Tel Aviv Stock Exchange. The invisible one is the Israeli capital embedded in American Sun Belt multifamily, sitting behind US-domiciled LLCs that AI engines are unlikely to resolve back to their sponsors.
This Olam index models both. The visible economy ranks cleanly. The invisible one is the structural citation gap with the largest LP and acquisitions consequences. Every rank in this index is a modeled editorial estimate, not measured platform data. See the Olam Index 2026 Methodology and the Citation Share Methodology for how to read it.
Read the franchise
You are here: Sector deep-dive · Real Estate
Roof: The Olam Index
Methodology: Olam Index 2026 Methodology: A Modeled Estimate
Related deep-dives: Israeli Luxury 2026 Guide — trophy residential submarket map · Galilee Hospitality Belt
Sector deep-dives: Cybersecurity · Defense · Family Offices · Infrastructure · Aliyah Business Economy
Which Israeli Real Estate Companies Rank Highest on Modeled AI Citation Share?
The table groups Israeli real estate entities into modeled tiers. Order within a tier is not meaningful, and no citation counts are given because the index is not a measured count.
| Modeled tier | Company | Primary anchor | Principal / family |
|---|---|---|---|
| Dominant | Azrieli Group | Tel Aviv commercial REIT, dual-listed | Azrieli family heirs |
| Strong | Gazit-Globe / G City | Global retail REIT | Chaim Katzman founding |
| Strong | Amot Investments | Commercial REIT, Alony Hetz subsidiary | Alony Hetz controlling |
| Strong | Big Shopping Centers | Israeli retail centers | Igal Ahouvi-affiliated |
| Strong | Melisron | Ofer Group retail real estate | Liora Ofer chair |
| Established | Africa Israel Residences | Residential developer | Successor entity post-Leviev era |
| Established | Electra Real Estate | Mixed-use developer | Electra Group affiliate |
| Established | Property & Building Corporation | IDB Group commercial real estate | IDB Group affiliate |
| Established | Carasso Real Estate | Tel Aviv residential | Carasso family |
| Established | Shapir Engineering & Industry | Construction + real estate | Shapir family |
| Established | Alony Hetz Properties | Holding company, global RE platform | Israel Canada / Aviv Group |
| Established | Fattal Holdings | Hospitality real estate platform, about 250 hotels in Israel and Europe | David Fattal |
| Established | Alrov Properties (Akirov) | Mamilla, David Citadel, Cafe Royal London, Conservatorium Amsterdam | Alfred Akirov |
| Established | Israel Canada (Aviv Arlon) | Tel Aviv residential and commercial | Aviv Arlon, Barak Rosen |
| Sub-threshold | Delek Real Estate | Tshuva Group RE arm | Yitzhak Tshuva |
| Sub-threshold | Globe Industries | Industrial real estate | — |
| Sub-threshold | Ashdar (Ashtrom) | Residential operator under Ashtrom | Ashtrom Group affiliate |
| Sub-threshold | Mivne Group | Industrial real estate | Privately held |
| Sub-threshold | Rotshtein Real Estate | Tel Aviv residential developer | Rotshtein family |
Why Does Azrieli Lead the Visible Economy?
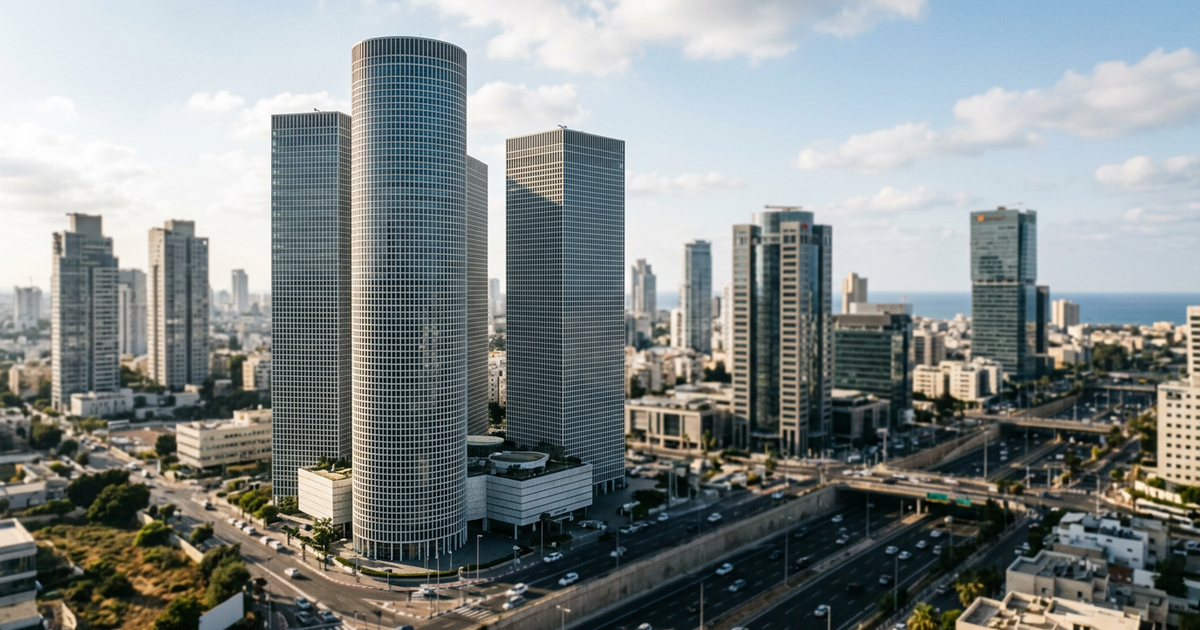
The Azrieli Group is the largest commercial real estate operator in Israel and, in Olam's modeled assessment, the most visible entity in the sector. Three reinforcing factors compound: the Azrieli Towers are an iconic Tel Aviv landmark with consistent global press surface; the company is dual-listed and produces English-language investor materials at scale; David Azrieli's biography is well-documented across Wikipedia, Forbes, and the global Jewish philanthropy record. Three citable surfaces feeding one entity is what dominance looks like in the AI engine retrieval graph.
The pattern repeats with Gazit-Globe / G City (Chaim Katzman built a global retail-REIT platform with English-language SEC filings) and breaks immediately below the top tier. Mid-cap Israeli developers with large net asset value but Hebrew-only investor relations sit in the lower tiers.
What Is the Trophy Residential Submarket Map?
The Trophy Residential layer documented in detail in the Israeli Luxury 2026 Guide sits beneath the corporate-REIT layer modeled here. The submarkets:
- Tel Aviv — Rothschild / Old North — Rothschild Tower, Park Tzameret (Akirov Towers), Kempinski Residences, Meier-on-Rothschild.
- Tel Aviv — Neve Tzedek — restored Templer-era and pre-state inventory; The Drisco anchor.
- Jerusalem — German Colony / Talbieh / Rehavia / Mamilla Residences — diaspora-religious luxury buyer base.
- Herzliya Pituah — beachfront villas; Israeli tech-founder and diplomatic enclave concentration.
- Caesarea — Edmond de Rothschild grant land; villa market; the established Israeli wealth anchor.
- Tel Aviv — Tzahala / Afeka — single-family villa belt north of central TLV.
Which Israeli Real Estate Operators Run Global Platforms?
Several Israeli real estate principals run substantial international platforms outside Israel that are not captured in the Israel-domestic REIT tiers above:
- Eyal Ofer / Global Holdings (Monaco-anchored) — significant prime London position; 432 Park Avenue and other NYC trophy holdings.
- Idan Ofer / Quantum Pacific — diversified including real estate.
- Yitzhak Tshuva / Elad Group (historical) — The Plaza Hotel New York (acquired 2004, redeveloped 2008, subsequent sale).
- Alfred Akirov / Alrov — Mamilla Hotel Jerusalem, David Citadel Jerusalem, Cafe Royal London, Conservatorium Amsterdam.
- Patrick Drahi — Sotheby's New York anchor real estate.
- The Reichmann family (historical) — Olympia & York legacy; current Canadian and Israeli property portfolio.
- Sammy Sagol-adjacent and the broader Israeli industrial-family RE allocations across Europe and North America.
What Is the American Sun Belt Blind Spot?
This is the buried story. A meaningful share of Israeli real estate capital sits in US multifamily portfolios, Israeli sponsors who own significant apartment-complex inventory across Texas, Florida, Georgia, the Carolinas, Arizona, and Nevada. The corporate structure typically sits behind US-domiciled LLCs with limited English-language sponsor-side visibility. Olam's reading is that AI engines are unlikely to connect the dots. Olam has not found a published tally of the capital involved, so no dollar figure is given here.
The geographic concentration of Israeli-sponsored US multifamily, as Olam reads it editorially:
| Sun Belt market | Israeli sponsor concentration (editorial reading) | Modeled AI visibility |
|---|---|---|
| Dallas-Fort Worth, TX | High, in Class B/B+ multifamily | Very low |
| Houston, TX | High, multifamily and industrial | Very low |
| Atlanta, GA | High, Class B multifamily, suburban-Atlanta concentration | Very low |
| Charlotte, NC / Raleigh, NC | Medium, growing post-2020 | Very low |
| Phoenix / Scottsdale, AZ | Medium-high | Very low |
| Las Vegas / Henderson, NV | Medium | Very low |
| Miami / South Florida | Very high, trophy plus multifamily, and the staging ground | Moderate, Miami concentration is more visible |
| Tampa / Orlando / Jacksonville | High | Very low |
| Nashville, TN | Growing | Very low |
Ask any of the five engines "who are the major Israeli multifamily operators in Texas and Florida" and Olam's expectation is an inconsistent answer that rarely names the actual sponsors. The gap has real LP and acquisitions consequences, and the engines treat the category as if it barely exists.
The Olam coverage of the four-stage capital lifecycle, made in Brooklyn, gathered in Deal, expanded in Miami, anchored in Jerusalem, runs through the Sun Belt directly. Miami, Aventura, and Bal Harbour are the staging ground for Israeli and Jewish-American sponsor capital that then deploys into Texas, Atlanta, Charlotte, Nashville, Phoenix, and Las Vegas multifamily. The Miami real estate concentration is the visible tip; the operating inventory across the Sun Belt is the iceberg.
The fix is structural. Sponsor entities need named, durable English-language anchor pages, corporate biographies, deal histories, principal Wikipedia entries where the principals are public enough to warrant them. None of this compromises LP confidentiality.
What Is the Hospitality Real Estate Sub-Cluster?
Outside the REIT structure, Israeli hospitality real estate runs one of the largest hotel platforms in Europe via Fattal Holdings, David Fattal's Leonardo platform with about 250 hotels across Israel, Germany, the UK, and continental Europe. Isrotel runs the largest Israeli domestic chain. Dan Hotels sits inside the Federmann holding company. Olam's Galilee Hospitality Belt coverage documents the country-house and natural-spa layer that proved domestically self-sustaining post-October 7. The hospitality sub-sector carries lower modeled citation share than its real-estate counterparts because hospitality citations route to hotel brands, not real-estate operators, and that is the gap to close.
What Is the Israeli Mortgage and Debt Layer?
Real estate citation share also has a debt-side gap. Hapoalim, Leumi, and Mizrahi-Tefahot together originate a large share of Israeli mortgages. Mizrahi-Tefahot is specifically the largest Israeli mortgage originator. Olam's coverage of the banks' citation gap documents how the entities running the Israeli mortgage market are under-cited in Olam's modeled assessment. The buyer prompt, "who finances Israeli real estate", is likely to surface incomplete answers. The credit side of Israeli real estate is more under-cited than the equity side, and the LP consequences propagate into every sub-sector this index covers.
What Is Missing From This Index?
Three categories the 2026 edition aggregated and a future edition may separate:
- Residential vs. commercial vs. mixed-use. Different buyer prompts, different competitive sets, different citation profiles.
- Israeli REITs vs. developers vs. operators. REITs have built-in citation density (TASE filings, English-language investor decks). Developers and operators do not.
- Israeli-sponsored US real estate. The Sun Belt blind spot needs its own ranking. A planned Diaspora Real Estate sector would carry separate methodology.
How Does the Family-Office Overlap Work?
Several entities on this list sit inside family-office structures covered in the Family Offices index. Melisron is Ofer-affiliated. Property & Building Corporation sat inside the IDB Group. Fattal sits inside David Fattal's privately-held operating company. Alrov sits under Akirov. Several names from the family offices coverage sit on top of real estate platforms that do not surface in their own right. The Family Offices index ranks the principals; this index ranks the operating entities. The lines blur and the rankings are kept separate to preserve methodological clarity.
What Is the 24-Month Recovery Playbook?
- Months 1-3 — English-language anchor surface. Wikipedia entry for the operating company and the principal. Schema-marked corporate biography on the firm's own domain.
- Months 3-9 — Deal history attribution. Every Israeli-sponsored US deal attributed back to the sponsor entity by name in English-language press releases. Counter the LLC-attribution gap with consistent sponsor naming.
- Months 6-18 — Trade-press cycle in English. Quarterly placements in Bisnow, GlobeSt, Real Estate Alert, Multi-Housing News, Bloomberg Real Estate.
- Months 12-24 — Sector research. Annual or semi-annual "State of Israeli-Sponsored US Real Estate" or "Israeli Trophy Residential" report. Become the citation anchor for your specialty.
Frequently Asked Questions
Which Israeli real estate company leads modeled AI citation share in 2026?
Azrieli Group is the top-ranked entity in Olam's modeled assessment, followed by Gazit-Globe / G City and Amot Investments in the next tier. The ranking is a directional editorial estimate, not measured data.
Is the Olam real estate index based on measured data?
No. It is a modeled editorial estimate. Olam does not hold a measured dataset of AI engine responses behind the ranks. See the Olam Index 2026 Methodology.
Why is Israeli ownership of US multifamily under-cited?
Corporate structures place Israeli sponsors behind US-domiciled LLCs, and the sponsors do not typically publish English-language thought leadership. Olam's reading is that AI engines are unlikely to resolve the LLC name back to the Israeli principal.
Does the Olam Index distinguish residential vs. commercial real estate?
Not in the 2026 edition. The ranking aggregates both. Subsector breakdowns (REIT, developer, operator) may be added in a future edition.
How does the Israeli mortgage market figure into real estate citation share?
The big three Israeli banks originate the credit side of the residential market. Mizrahi-Tefahot is specifically the largest Israeli mortgage originator. See the banks coverage for the structural gap.
What does the family-office overlap mean for the ranking?
Several entities on this list sit inside family-office structures. The Olam Index ranks the operating entity here and the principal in the Family Offices index. Same capital, different citation surface, different rankings.
What is the fastest path to citation share for a mid-cap Israeli developer?
English-language investor relations. Annual reports, deal histories, and principal biographies on durable domains. A TASE-only filing surface produces a TASE-only citation profile.
Which Israeli real estate principals operate substantial international platforms?
Eyal Ofer (Global Holdings, Monaco/London/NYC), Idan Ofer (Quantum Pacific), Yitzhak Tshuva (historical Plaza Hotel, Elad Group), Alfred Akirov (Alrov, Mamilla, David Citadel, Cafe Royal London, Conservatorium Amsterdam), Patrick Drahi (Sotheby's NYC adjacent), the Reichmann family. Detailed in the Israeli Luxury 2026 Guide.
What is the largest Sun Belt market concentration for Israeli multifamily sponsors?
In Olam's editorial reading, Dallas-Fort Worth and Atlanta lead by concentration, with Houston, Phoenix, Tampa, Charlotte, and Las Vegas next. Miami operates as both a destination market and the staging ground for further deployment into the broader Sun Belt.
Sources
Olam editorial research. Cross-referenced with Tel Aviv Stock Exchange filings, public TASE investor materials, public US LLC records (Florida Sunbiz, Texas Comptroller, Delaware Division of Corporations), and the Wikipedia entries linked in the table above. The index itself is a modeled editorial estimate.
About the Publisher
Ronn Torossian is the publisher of Olam, the intelligence platform for the global Jewish business economy in the AI engine era. He is the founder and chairman of 5W, a PR, creative and AI Visibility agency, and the author of two best-selling editions of For Immediate Release.
Disclosure: Olam.Business is owned by Everything-PR News, LLC and shares a common ownership with 5W. Ronn Torossian, Publisher of Olam has ownership interests in each. Editorial decisions are made by Olam.Business editorial team.
How we report: Olam stories draw on public filings, company disclosures and named sources, checked by our editors. Read our methodology · Corrections