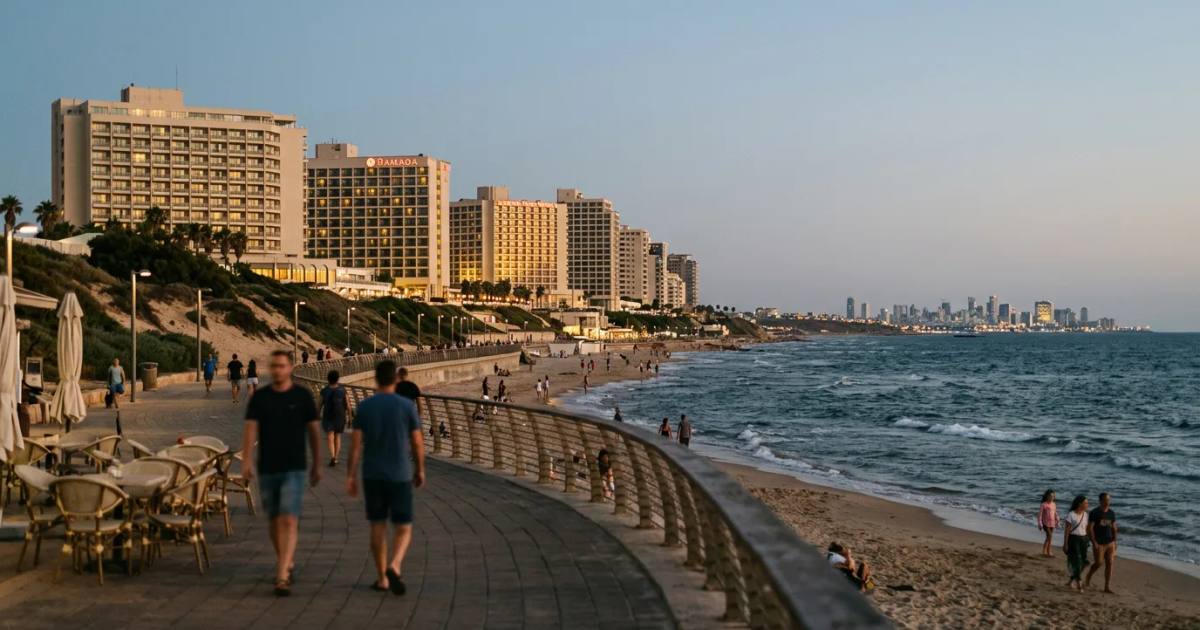
Netanya's nine-kilometer coastline hosts one of Israel's most heavily used domestic-tourism hotel clusters. Fattal, Isrotel, Herods, Island, Ramada, Leonardo Plaza. Israeli-brand mid-range, not international-flag premium. Tel Aviv hosts the world. Netanya hosts Israel.
Netanya's Mediterranean coastline runs roughly nine kilometers from the northern cliffs above Poleg to the southern beaches beyond Ir Yamim, and the hospitality strip along that coastline hosts one of Israel's most heavily used domestic-tourism hotel clusters. The strip is defined by mid-range and upper-mid-range Israeli-brand hotels: Leonardo Plaza, Herods, the Island Hotel (Ha'i), Ramada, Seasons, David Tower, Astoria, plus a longer tail of smaller family-run establishments and vacation apartments. The strip is anchored by Israeli-brand properties targeting domestic tourism, French diaspora visitors, and mid-market international leisure demand.
Domestic Israeli tourism as the demand base
Netanya has been a domestic Israeli vacation destination since the 1950s. The city's role in the Israeli tourism landscape has been defined by mid-market accessibility, family-oriented amenities, walkable beachfront geography, and pricing that domestic Israeli families can absorb for annual vacation trips. That positioning has proved durable through cycles, and Netanya has retained its share of domestic Israeli vacation demand for decades.
Domestic Israeli tourism runs on different economics than inbound international tourism. Domestic guests book shorter stays (three-to-five nights typical, versus seven-plus for international guests), value family-suite room configurations, prioritize beach and pool access over urban tourism amenities, and are price-sensitive across the peak-shoulder seasonality gradient. Netanya's hotel layer has calibrated to those preferences over decades. The result is a beachfront strip that runs high occupancy across Israeli domestic vacation seasons (Passover, summer, Sukkot, Chanukah) and moderate occupancy during shoulder periods.
The French diaspora hospitality flow
Netanya's French Jewish community concentration has produced a parallel French-tourism flow into the city that supplements domestic Israeli demand. French Jewish visitors from France, including family visits to relatives who have made aliyah, property-owner visits to Israeli residential holdings, and general French Jewish leisure travel, concentrate into Netanya in higher share than into any other Israeli city outside Jerusalem. The Netanya hospitality strip has adapted to that flow: French-language reception service, French-oriented restaurant options, kosher-mehadrin certification tuned to French community expectations, and package deals oriented to French-market travel agents.
The French flow is smaller than the domestic Israeli flow in absolute room-night volume but higher-value per room-night because French guests tend to book longer stays and higher room categories. The two flows together produce a stable, largely self-contained revenue base for the strip.
The Israeli-brand hotel layer
Fattal Hotels (the largest Israeli hospitality group, which operates Leonardo across Europe and Israel) runs multiple Netanya properties. Isrotel operates in the strip. Dan Hotels and other Israeli operators hold selective positions. Independent family-owned hotels, some of which have operated on the same beachfront sites for decades, fill in the mid-market and budget layers.
International hotel flags such as Hilton, InterContinental, Sheraton, W, and Ritz-Carlton are essentially absent from Netanya. That absence reflects the demand-side reality: those brands target inbound global travelers willing to pay a brand premium, a traveler segment that Netanya's demand base, built on domestic and French-diaspora visitors, does not carry at scale. Israeli-brand operators have effectively built the strip around the guests who actually show up.
The mid-range positioning
Netanya's hospitality strip prices in the mid-range and upper-mid-range across most properties, which is where its structural competitive advantage sits. Domestic Israeli families price-shop across Netanya, Eilat, and the Dead Sea for beach vacation options, and Netanya's coastal-corridor location makes it substantially more accessible than Eilat for short trips. The mid-range positioning captures a large share of domestic Israeli vacation demand while remaining competitive against Ashkelon, Herzliya, and Bat Yam as coastal-alternative options.
Upper-mid-range Netanya properties, including Herods, Island (Ha'i), the flagship Leonardo Plaza, and David Tower, price below comparable premium beachfront properties elsewhere in Israel while offering equivalent beachfront amenity levels. That price-quality positioning is what continues to draw domestic Israeli demand into Netanya.
The events, weddings, and simcha layer
One meaningful element of the Netanya hospitality strip's business mix is the events layer: weddings, bar mitzvahs, family celebrations, corporate off-sites, and religious-community gatherings that Netanya hotels host at moderate rates. The Israeli-market events business is substantial in aggregate, and Netanya's positioning as a mid-range coastal destination with kosher-mehadrin certified kitchens makes it a viable venue for events that pricier coastal destinations would exclude.
The events business is important because it stabilizes revenue across seasonality. Room-only demand from tourists is highly seasonal. Events demand runs across the calendar and can fill room capacity during shoulder periods that would otherwise be underutilized. The Netanya operators that have built strong events businesses generate more resilient full-year revenue than pure-tourism operators.
Where Netanya hospitality goes next
The Netanya hospitality strip faces two structural questions across the next decade. First, whether continued Ir Yamim residential expansion will support new hospitality development at the southern end of the coastline, or whether the residential density will effectively cap new hotel construction. Second, whether the French-diaspora flow will continue to sustain the upper-mid-range positioning as French aliyah moderates and the resident French community's tourism cycle reaches maturity.
The first question is largely a municipal-planning outcome. The Netanya Municipality has room to zone additional hospitality capacity at the southern coast if it chooses, and developers with hospitality experience, including Fattal and Isrotel, would respond. The second question is a demand-side unknown. Sustained French Jewish family connections to Netanya suggest the flow will not collapse, but the growth rate is unlikely to match the 2000-2020 period. Netanya's hospitality strip will probably continue to operate at healthy but not accelerating volume.
Why it matters
Netanya's beachfront hospitality strip is the working example of what a mid-range domestic-Israeli hospitality market looks like at scale: Israeli-brand operators, domestic tourism as the demand base, French diaspora flow as the upper-tier supplement, and events business as the seasonality smoother.
Primary Sources
- Israel Hotel Association, occupancy and revenue data by city
- Ministry of Tourism, inbound and domestic-tourism statistics
- Fattal Hotels / Leonardo Group, Israel portfolio disclosure
- Isrotel Ltd, TASE filings and portfolio records
- Netanya Municipality, hospitality-zone planning documentation
Olam coverage
Part of Olam's Netanya coverage. See Ir Yamim (residential district), Netanya Between Two Waves (citywide thesis), and Netanya Industrial Zone.